Colorado Down Payment Assistance: Can It Cover Closing Costs, Carpet, Paint, and Backyard Improvements?
Down payment assistance may help cover more than you think. And with the right strategy, you could have money left over to make your new house feel like home.
You've found a house you love. The neighborhood is great, the price works, and you can already picture yourself living there.
But there's one problem.
The carpet needs replacing. The walls could use fresh paint. And the backyard? Let's just say it needs some attention.
You're already wondering how to afford the down payment and closing costs. Where is the money for those improvements supposed to come from?
Here's something many Colorado homebuyers don't realize: Down payment assistance can cover both your down payment and closing costs. And with the right seller, you might even negotiate improvements before moving in.
Let's explore how it works, including a real home purchase we recently helped complete in Monument, Colorado.
Down Payment Assistance Isn't Just for Down Payments
Despite its name, down payment assistance isn't always limited to your down payment.
Depending on the program, eligible funds may help cover:
- Your down payment
- Mortgage closing costs
- Certain prepaid expenses, including homeowners insurance and property taxes
- Other approved homebuying expenses
Colorado offers several assistance programs, including grants and second mortgage options.
Some grants don't require repayment when program conditions are satisfied. Other programs provide loans that may require repayment when you sell, refinance, or reach another specified event.
The important thing is finding assistance that works for your financial situation, not simply choosing the program offering the largest amount.
Can Down Payment Assistance Pay for New Carpet or Paint?
Usually, not directly.
Traditional down payment assistance programs are designed to help you purchase a home, not provide extra cash for remodeling or decorating.
That means you generally can't take unused assistance funds and spend them on carpet, painting, landscaping, appliances, or furniture.
But that doesn't mean you're out of options.
The strategy is using assistance to reduce your upfront homebuying expenses while negotiating with the seller for certain improvements.
And we recently saw exactly how well that strategy can work.
A Real Colorado Homebuyer Success Story: A $450,000 Home for Just $1,000 Out of Pocket
We recently helped sell a beautiful, newer home in Monument, Colorado, and the transaction is a great example of what's possible when down payment assistance and seller negotiations come together.
The home was priced at $450,000, and the seller was highly motivated to sell.
Our buyers loved the property, but there were a few things they wanted to change.
The carpet needed replacing, they wanted new tile, and the backyard could use some landscaping improvements.
Normally, those projects could cost thousands of dollars on top of the down payment and closing costs.
But here's where things got interesting.
The buyers qualified for a down payment assistance program that covered their entire down payment and all their closing costs.
Even better, because the seller was motivated, we negotiated for the seller to pay for:
- New carpet
- New tile
- Landscaping improvements in the backyard
And the best part?
The buyers purchased their $450,000 home with just $1,000 out of pocket, which was the minimum contribution required by their particular down payment assistance program.
Think about that.
They purchased a newer $450,000 home, received help covering their down payment and closing costs, and had several improvements paid for by the seller.
That's the power of understanding your financing options and working with real estate professionals who know how to negotiate.
Of course, not every seller will agree to these terms, and not every buyer will qualify for the same assistance.
But this transaction demonstrates why it's worth exploring your options before assuming you need tens of thousands of dollars saved to purchase a home.
What If the Seller Pays Your Closing Costs?
When purchasing a home, you may be able to negotiate for the seller to contribute toward your closing costs.
These contributions are commonly called seller concessions.
Instead of asking the seller to reduce the purchase price, you might negotiate for the seller to cover some of your eligible closing expenses.
For example, imagine you're purchasing a $400,000 home.
Your estimated expenses might look like this:
| Expense | Amount |
| Down payment (3.5%) | $14,000 |
| Closing costs and prepaids | $10,000 |
| Total upfront expenses | $24,000 |
Now imagine you qualify for $14,000 in down payment assistance, and the seller agrees to contribute $8,000 toward eligible closing costs.
Your remaining upfront expenses could be approximately $2,000, assuming the assistance and concessions are permitted together and no additional borrower contribution is required.
That's a significant difference.
Instead of spending $24,000 of your savings, you might preserve much of that money for moving expenses, emergency savings, or home improvements.
Seller concessions cannot simply be handed to you as cash for remodeling. Mortgage guidelines determine how much the seller can contribute and which expenses qualify.
How Do I Get the Carpet, Paint, and Backyard Paid For?
There are several possibilities worth exploring.
Option 1: Keep More of Your Own Money
Use eligible down payment assistance and negotiated seller concessions to reduce the amount you need at closing.
Then use your remaining savings for improvements after purchasing the home.
For example, you might budget $2,500 for carpet, $1,500 for painting, and $2,000 for backyard improvements.
That's $6,000 in improvements you might otherwise have postponed.
Option 2: Ask the Seller to Make Improvements
As our Monument transaction demonstrates, a motivated seller may agree to make certain improvements before closing.
Perhaps you want new flooring, fresh paint, or landscaping work.
Your real estate professional can help negotiate those requests and ensure they're properly documented in the purchase agreement.
Option 3: Explore Renovation Financing
Certain mortgage programs allow qualified buyers to finance eligible repairs and improvements as part of their home purchase.
Options may include FHA 203(k) or conventional renovation mortgages.
Depending on program requirements, projects might include flooring, painting, or exterior improvements.
Renovation loans involve additional documentation, contractor requirements, and approval procedures. Not every assistance program can be combined with renovation financing.
Not Every Mortgage Lender Offers Every Assistance Program
Here's something important that many Colorado homebuyers don't know.
Not every bank, credit union, or mortgage lender is approved to offer every Colorado down payment assistance program.
Some programs require participating lenders. Others have specific income limits, credit requirements, purchase price restrictions, or property eligibility guidelines.
And not every program allows the same combinations of assistance, seller concessions, and renovation financing.
That's why choosing the right mortgage professional matters.
An experienced lender can help you compare available programs, understand repayment obligations, estimate your cash needed at closing, and determine whether assistance can work with your preferred financing strategy.
Your real estate professional can then help you identify suitable homes and negotiate terms that support your goals.
Your First Home Doesn't Have to Be Your Forever Home
One mistake first-time buyers make is expecting their first house to be their dream home.
It doesn't have to be.
Maybe the kitchen isn't your favorite color. Maybe the carpet has seen better days. Maybe the backyard needs serious attention.
Those things can often be improved over time.
What matters is finding a home you can comfortably afford, in a location that works for your needs.
As you make mortgage payments, you may build equity through principal reduction and potentially benefit from future appreciation, although home values can also decline.
Your first home is an opportunity to get started, not a requirement to have everything figured out.
Find Out What Colorado Homebuyer Assistance You May Qualify For
At Colorado First Time Home Buyer, we help connect buyers with Colorado-licensed mortgage professionals and experienced real estate professionals who can explore grants, down payment assistance, seller concessions, and financing options.
You can even start with a free soft credit check that won't impact your credit score.
Remember our Monument homebuyers?
They purchased a $450,000 home with just $1,000 out of pocket and negotiated new carpet, tile, and backyard landscaping.
Your situation may be different, but you won't know what's possible until you explore your options.
Before assuming you need thousands of dollars saved to buy a home, find out what assistance may be available.
Real People. Real Homes. Real Success Stories
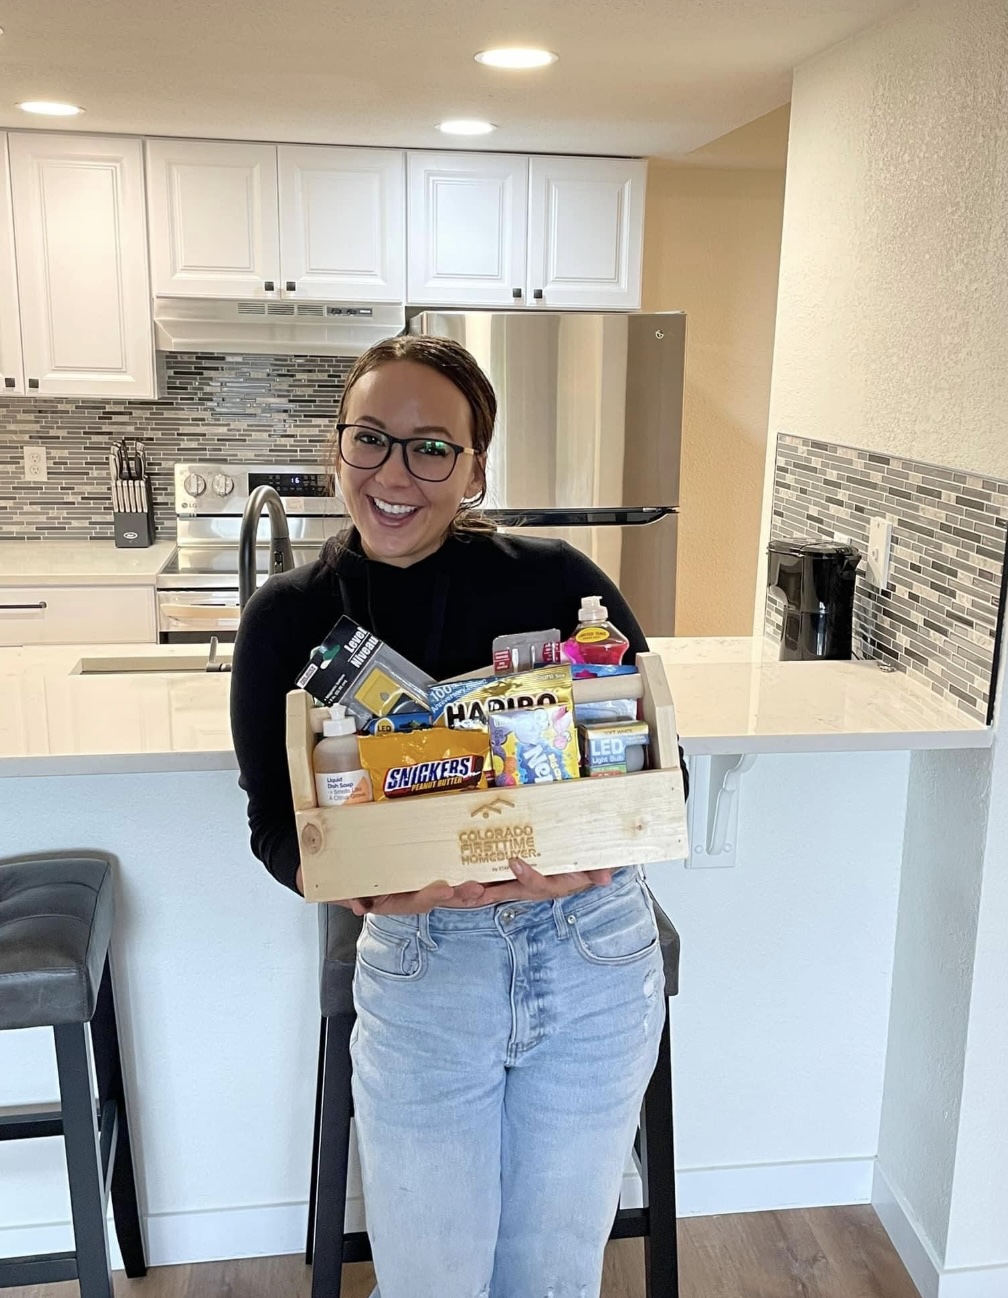
The photos featured in our blogs are of actual Colorado First Time Home Buyer clients who have taken the exciting step toward homeownership!
Want to see more happy homeowners? ⓕ Facebook ▷ YouTube