Your credit doesn't have to be perfect, and your savings don't have to be huge. You may be closer to owning a home than you realize.
If you've ever thought, "My credit isn't good enough," "I don't make enough money," or "I'll never save enough for a down payment," you're not alone.
Thousands of potential homebuyers put their dreams on hold because they assume they won't qualify for a mortgage.
But what if you're more qualified than you think?
Here's some encouraging news: You don't need perfect credit, a six-figure income, or 20% down to become a homeowner.
There are mortgage programs and down payment assistance options designed to help people with different financial situations.
Before you count yourself out, let's look at what's possible.
Your Credit Score Doesn't Have to Be Perfect
Think you need a 700 or 800 credit score to buy a home? Think again!
While higher credit scores can help you qualify for better mortgage terms, a lower score doesn't automatically mean you can't buy a home.
FHA loan programs may allow qualified buyers to purchase a home with a credit score as low as 580, and certain down payment assistance programs may be available to buyers with scores starting at 600.
That means you may have more options than you realize.
Do you know your credit score? If not, now is a great time to find out!
Colorado First Time Home Buyer offers a FREE soft credit check that won't hurt your credit score.
It's a simple, no-pressure way to understand where you stand and start exploring your homebuying options.
Check your credit for FREE today!
Remember, your credit score is just one piece of the puzzle. Lenders also consider your income, debts, employment, and overall financial situation.
A Free Credit Check Could Be Your First Step
You don't have to apply for a mortgage just to find out whether homeownership might be possible.
Start with a free soft credit check through Colorado First Time Home Buyer.
Unlike a hard credit inquiry, a soft credit check won't lower your credit score.
It's an easy way to begin understanding your financial picture.
Your credit review can help you:
- Understand your current credit scores.
- See whether you may meet mortgage program requirements.
- Identify potential obstacles to qualifying.
- Discover steps that could improve your options.
Even if your credit isn't quite where it needs to be, that's okay. Knowing what to work on is a great first step.
A soft credit check isn't a mortgage approval, and lenders may use different scoring models, but it can help you get started with confidence.
You May Qualify for Up to $25,000 in Down Payment Assistance
What if saving a large down payment isn't the obstacle you thought it was?
One of the biggest reasons people delay buying a home is the belief that they need tens of thousands of dollars saved.
Fortunately, Colorado has grant and down payment assistance options that may help eligible homebuyers.
Some qualifying first-generation homebuyers may be eligible for up to $25,000 in assistance, depending on the program, funding availability, and eligibility requirements.
Other programs may help cover down payments or closing costs.
Assistance can come in several forms, including grants, forgivable loans, or repayable second mortgages.
And here's something worth remembering:
You don't need 20% down to buy a home!
With available down payment grants and assistance programs, qualified Colorado homebuyers may need very little money out of pocket to get started.
You might be surprised at just how achievable homeownership can be!
Have Credit Card Debt or a Car Payment? Don't Count Yourself Out!
Almost everyone has some kind of monthly debt.
Maybe you're making car payments, paying off credit cards, or managing student loans.
That doesn't automatically mean you can't qualify for a mortgage.
Lenders look at your debt-to-income ratio, which compares your required monthly debt payments with your income before taxes.
For example, if you earn $5,000 a month and have $1,000 in monthly debt payments, your current debt-to-income ratio is 20% before adding a mortgage payment.
Depending on your income, credit, and mortgage program, you may still qualify.
Sometimes even small changes, like paying down a credit card balance, can improve your buying power.
You don't necessarily have to be debt-free to become a homeowner.
Had Financial Challenges in the Past? Your Story Isn't Over
Life doesn't always go according to plan.
Maybe you've experienced a divorce, job loss, unexpected medical expenses, or a difficult financial period.
Those experiences don't have to define your financial future.
Many buyers who have experienced collections, bankruptcy, or foreclosure may still have opportunities to qualify for a mortgage.
Some programs have waiting periods and additional requirements, but a financial setback doesn't necessarily close the door on homeownership forever.
What matters isn't just where you've been. It's also where you are today.
If you've been working to rebuild your finances, you may be making more progress than you realize.
Think You Don't Make Enough Money? You Might Be Surprised
You don't have to earn $100,000 a year to buy a home.
Mortgage qualification depends on more than your salary.
Lenders consider your income, monthly debts, credit, available funds, and the home you're hoping to purchase.
Some buyers may qualify using multiple eligible income sources. Others may qualify with a spouse, partner, or co-borrower.
The important question isn't whether you make a certain amount of money.
It's how much home you can comfortably afford based on your financial situation.
You may have options that haven't even crossed your mind.
Self-Employed or Recently Changed Jobs? You Still Have Options
Do you own a business, work on commission, or recently start a new job?
Don't assume that makes buying a home impossible.
Mortgage lenders generally look for stable, documented income, but that doesn't mean everyone needs a traditional salaried job.
Self-employed buyers may qualify using tax returns and other financial documentation.
And changing jobs, especially within the same industry, doesn't necessarily prevent mortgage approval.
Every situation is different, which is why talking with a mortgage professional can be so valuable.
Your career path doesn't have to look exactly like everyone else's to qualify for a home.
You Don't Have to Have Everything Figured Out Before Asking for Help
Here's something we wish more Colorado homebuyers knew:
You don't have to be ready to buy a home today to start exploring your options.
Too many people wait until they believe everything is perfect.
They want a higher credit score, more money saved, or every credit card paid off before speaking with a lender.
And while improving your finances is always worthwhile, you may not need to wait as long as you think.
Some buyers discover they're already in a position to purchase.
Others learn that a few manageable changes could help them qualify in the future.
Either way, understanding your options gives you something valuable: a plan.
Instead of wondering whether you'll ever qualify, you can start taking meaningful steps toward your goal.
Your Dream of Homeownership May Be Closer Than You Think
Buying your first home is a big milestone, and it's natural to have questions or doubts along the way.
But don't let assumptions about your credit, income, or savings stop you from exploring what's possible.
At Colorado First Time Home Buyer, we help people just like you understand their mortgage options, explore available grants and down payment assistance, and discover what it may take to become a homeowner.
You don't need perfect finances to start the conversation. You just need to take the first step.
Start with a FREE soft credit check that won't impact your credit score.
Whether you're ready to buy now or simply want to understand what you need to do next, we're here to help.
Real People. Real Homes. Real Success Stories
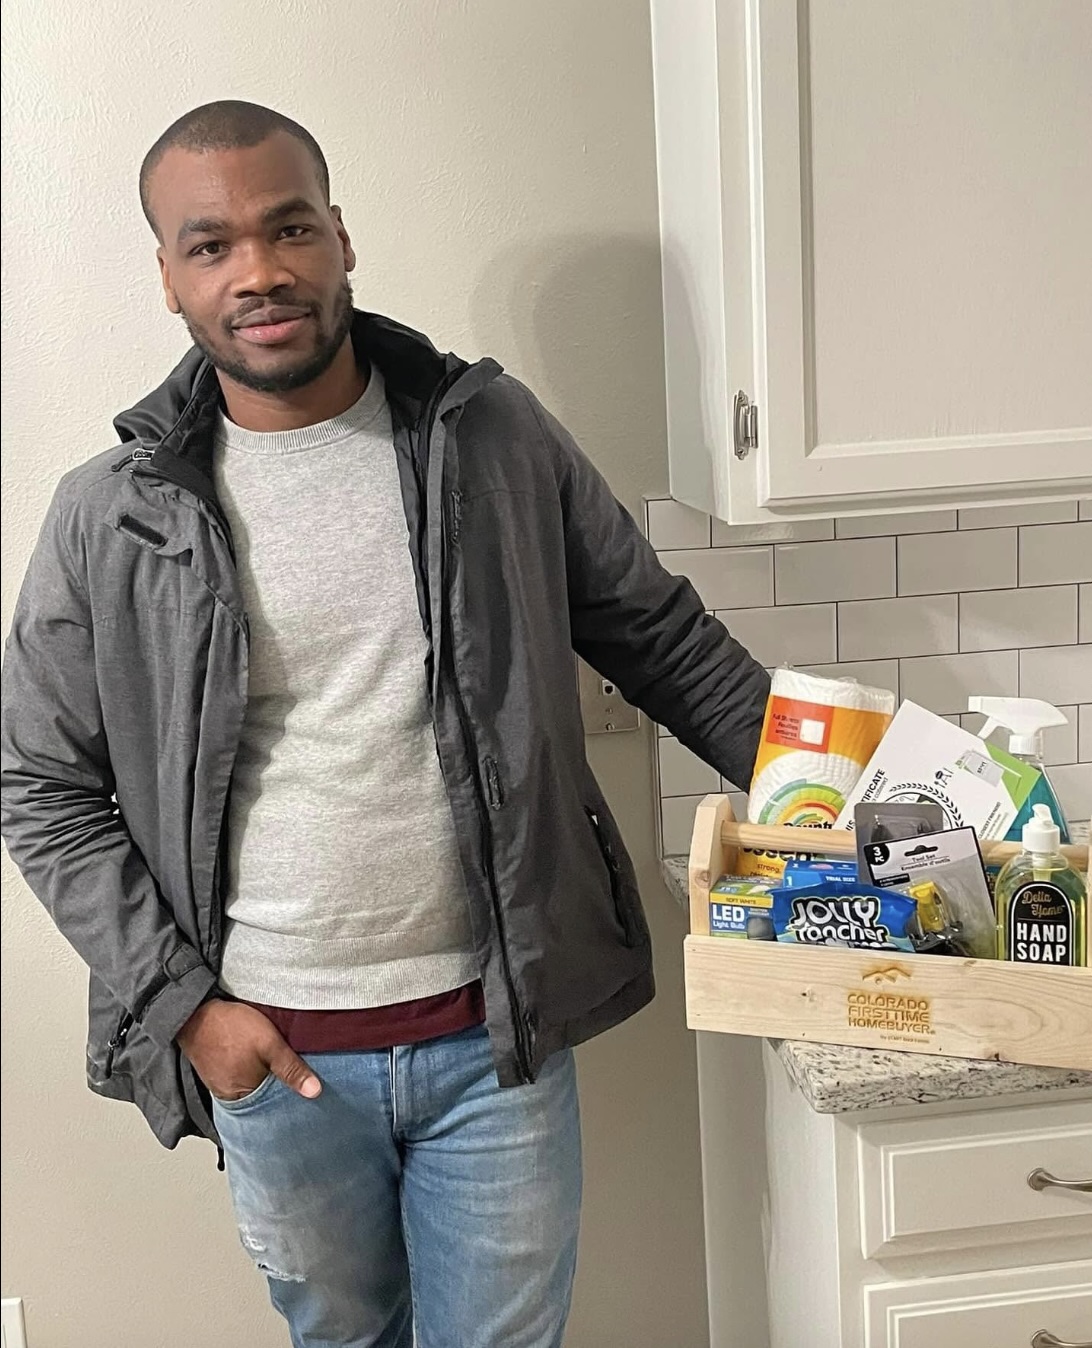
The photos featured in our blogs are of actual Colorado First Time Home Buyer clients who have taken the exciting step toward homeownership!
Want to see more happy homeowners? ⓕ Facebook ▷ YouTube